Water Mitigation vs Restoration: What's the Difference?
Mitigation and restoration are two different phases of recovering from water damage. Here's what each one means — and how they fit together.
Read guide →Water damage in a DC condo raises one urgent question: who pays? Here's a general overview of unit owner vs HOA responsibilities — not legal advice.
When water damages a condominium, the first question is always the same: who pays for the repairs? The general answer is that responsibility depends on where the water came from and which parts of the building were damaged — but the lines are not always clean, and condo documents matter a great deal.
Important: This article is general information only, not legal advice. Condo bylaws and master insurance policies vary widely across Washington DC buildings, so review your own documents or consult a qualified professional about your specific situation.
As a general rule, the party responsible for the area where the leak originated is usually responsible for the resulting damage — but insurance often ends up involved regardless. Damage to your own unit's interior is typically your responsibility, handled through your HO6 condo insurance policy, while damage to common areas or building systems is typically the HOA's responsibility under the master policy. The messy part is the overlap: a leak from an upstairs neighbor's washing machine, for example, can trigger both policies at once.
Most condo declarations in Washington DC draw a line between the "unit" (your private living space) and the "common elements" (everything shared). Here is how that usually plays out:
These are the situations Washington DC condo owners run into most often:
This is one of the most common scenarios in DC condo buildings. If your upstairs neighbor's supply line, toilet, or appliance leaks into your ceiling, the neighbor is generally considered responsible for the source of the leak, while you typically handle repairs inside your own unit through your HO6 policy. In practice, neighbors often split costs or let insurance sort it out — but document everything and notify your HOA in writing either way.
If a pipe serving the building bursts in a wall chase, utility closet, or another common area, the HOA is generally responsible for the pipe repair and damage to common areas. Damage inside individual units is more complicated: some master policies cover it, while others stop at the unit boundary, leaving unit owners to claim on their HO6 policies.
If your own appliance or fixture causes the damage, you are generally responsible for repairs to your unit — and potentially for damage to neighboring units. This is exactly why HO6 policies exist, and many DC condo associations require owners to carry one.
Two policies usually come into play after condo water damage. The master policy, held by the HOA, covers the building itself — but its coverage level matters enormously. A "bare walls" policy covers only the structure and common elements, while an "all-in" policy may also cover the original interior finishes in each unit. Your HO6 condo policy covers your personal property, interior improvements, and liability to neighbors. When damage occurs, both policies may respond, and deductibles can be significant — some master policies carry high water-damage deductibles that get assessed back to unit owners.
Take these steps promptly to protect your home and your position with insurers:
Responsibility disputes can take weeks or months to resolve, but water damage does not wait. The safest approach is to document thoroughly, notify everyone in writing, and get professional drying started right away — then sort out who pays with your HOA and insurers. If you discover water damage in your Washington DC condo, call (202) 449-5074 to be connected with a local provider who can assess the damage and start the drying process while the insurance questions get sorted out.
Need help right now? Call (202) 449-5074 — open 24/7. Water Damage DC will connect you with a local provider in Washington, DC.
Quick answers related to this guide.
Water Damage Restoration covers the full job — from initial assessment and water removal through drying, cleanup, and repairs. We connect you with local providers in the Washington DC area.
Learn More →
When water damages your property, emergency water damage restoration brings every phase of recovery under one coordinated process. Call now and we'll connect you with a nearby provider.
Learn More →
Water Damage Insurance Claim Assistance helps you navigate the claims process with proper documentation and estimates. We connect you with local providers in the Washington DC area.
Learn More →
Contents Cleaning and Restoration gives your belongings the same careful attention your building receives. We connect you with local providers in the Washington DC area.
Learn More →
Mitigation and restoration are two different phases of recovering from water damage. Here's what each one means — and how they fit together.
Read guide →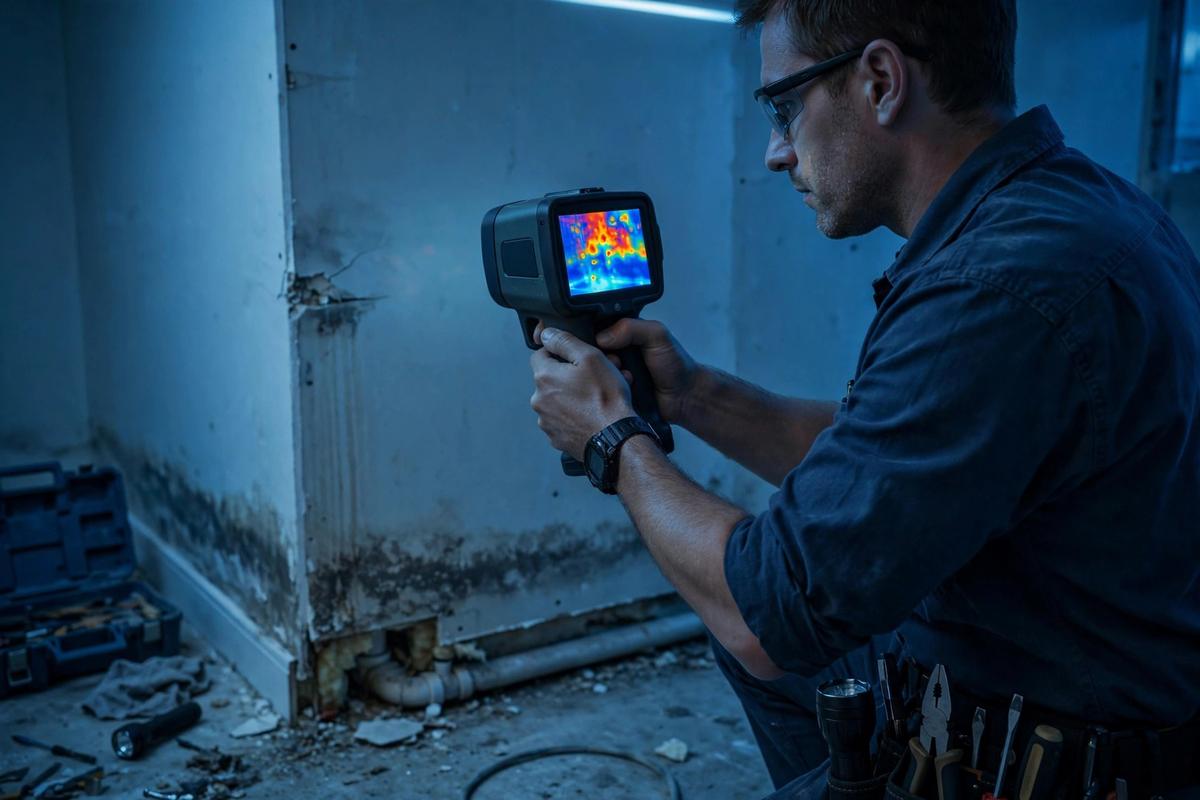
A professional water damage inspection maps hidden moisture with meters and thermal imaging, then produces a written scope of work. Here is what to expect.
Read guide →
The quality of your documentation can decide how smoothly your insurance claim goes. Learn the photo, video, and inventory protocol to follow before the adjuster arrives.
Read guide → Water Damage DC
Call Water Damage DC now and we'll connect you with a local provider in Washington, DC — no pressure, no obligation. Lines are open 24/7.
 Scan to call now